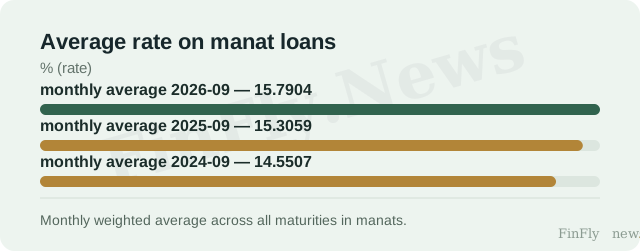
According to the Central Bank of Azerbaijan, the outstanding stock of loans to the economy at the end of August 2026 amounted to 34,884 million manats — 14.5% more than a year earlier and 2.1% more than a month earlier. At the same time, the average rate on manat loans for September 2026 was 15.79%, against 15.31% a year earlier and 14.55% two years earlier. The contrast is significant: the portfolio is growing at double-digit rates, while the price of a manat loan is not falling but gradually rising. This does not prove that the rate is holding back or spurring lending, but it shows that the expansion of debt is occurring in conditions of money that is not cheap but becoming more expensive.
What exactly the figures show
The outstanding stock of loans to the economy is the debt at the end of the month, not the amount of loans issued during the month. Therefore, the growth of the portfolio from 34,155 million manats at the end of July to 34,884 million at the end of August reflects a change in the accumulated stock, not the volume of new transactions. The annual comparison gives a broader picture: over twelve months the stock grew by 4,419 million manats. For context: at the end of 2025 it stood at 31,947 million, and in January 2026 — 31,864 million manats.
The rate is a separate series with a different nature. It is the monthly weighted average across all maturities in manats, not the rate on new contracts. Its movement from 14.55% in September 2024 to 15.31% in September 2025 and 15.79% in September 2026 describes a gradual increase in cost, not a one-off jump. The stock of debt and the rate can be compared as two characteristics of the same market, but not as cause and effect.
What this means for a borrower and what it does not prove
For a company planning to borrow in manats, the practical conclusion is a boundary for decision-making, not a signal to act. If the budget was based on last year's rate, the current level of around 15.8% means a higher cost of servicing, all else being equal. But one portfolio stock and one average rate do not say whether conditions have changed for a specific product, maturity or borrower. A decision to revise the credit budget, prices or procurement requires rates on new contracts of comparable maturity and data on actual lending, not only on the stock of debt.
The limitation here is fundamental: these tables do not imply that portfolio growth is caused by demand and that the rate is constraining it. The stock of debt can grow even with restrained new lending, and the average rate across all maturities is not equal to the rate on new transactions. The relationship between the price of credit and the dynamics of the portfolio requires separate data and cannot be derived from two series. The next comparable observation is the average rate on manat loans for October 2026 together with the portfolio stock at the end of September 2026: their joint movement will show whether the divergence between the expansion of the debt stock and the price of money persists.
The main point is not the growth of the portfolio itself, but the combination: debt to the economy is increasing at double-digit rates, while the average rate on manat loans is higher than the previous year's value for the third year in a row. This changes the framing of the discussion about the credit market: the question is not whether it is growing, but at what price. For businesses, this means that planning the cost of debt based on last year's benchmarks is becoming less reliable. But as long as we are talking about the stock of debt and the weighted average rate, rather than new lending and rates on new contracts, it is premature to draw conclusions about the availability of credit.