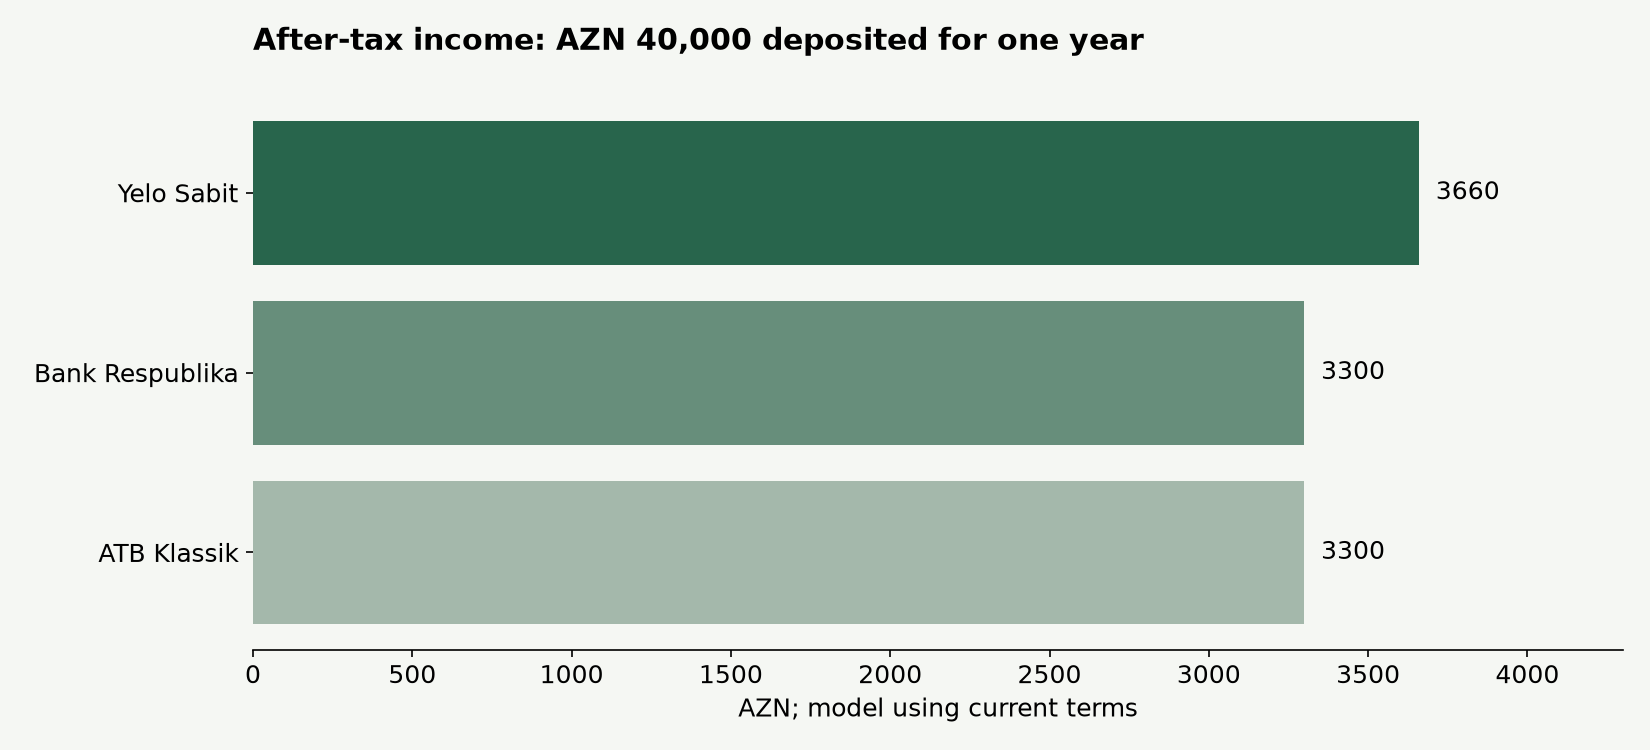
A 9.5% rate on an AZN 40,000 deposit produces AZN 3,800 in annual interest. Our model leaves AZN 3,660 after tax, or 9.15% of the original balance. Closing the same one-year contract on day 180 can reduce interest substantially. FinFly compares three products on equal terms: manat deposits, 12 months and interest paid at maturity.
A like-for-like comparison
Published terms checked on November 7 show 9.5% for Yelo Sabit and 8.5% for both Bank Respublika’s term deposit and ATB Klassik. This is a three-product sample, not a market-wide ranking. The model assumes no other interest income at the selected bank, no top-ups, fees or compounding. Returns are nominal and not adjusted for inflation. Current tax rules are assumed unchanged throughout the year; future legislative changes are not forecast.
| Product | Rate | Gross interest, AZN | Tax, AZN | Net interest, AZN | Net return |
|---|---|---|---|---|---|
| Yelo Sabit | 9.5% | 3800 | 140 | 3660 | 9.15% |
| Bank Respublika | 8.5% | 3400 | 100 | 3300 | 8.25% |
| ATB Klassik | 8.5% | 3400 | 100 | 3300 | 8.25% |
Why the tax is not 10% of all interest
Current rules exempt the first AZN 200 of monthly accrued interest on manat deposits at each bank; the remainder is taxed at 10%. For evenly accrued annual interest, our model uses an AZN 2,400 exemption: (3,800 - 2,400) × 10% = AZN 140. Actual withholding depends on the accrual calendar and other deposits held at that bank.
Interest rates versus access to cash
One percentage point on AZN 40,000 adds AZN 400 in gross annual interest. After tax, the difference between these products is AZN 360. If the money is needed before maturity, early-termination terms can matter more than that advantage.
Withdrawal on day 90 or day 180
The early-exit calculation uses a common 365-day year. Figures are interest before any tax adjustment, not individual bank quotations. They concern early termination of a one-year contract, rather than a separately purchased three- or six-month deposit.
| Product | Day 90 interest, AZN | Day 180 interest, AZN | Day 180 rule |
|---|---|---|---|
| Yelo Sabit | 0 | 562.19 | 30% of accrued interest |
| Bank Respublika | 0 | 167.67 | 10% of accrued interest |
| ATB Klassik | 0 | 0 | Under 12 months: 0% |
The early-exit calculation
Yelo’s modelled 180-day accrual is AZN 1,873.97; retaining 30% leaves AZN 562.19. Bank Respublika retains 10% of AZN 1,676.71, or AZN 167.67. Those retained shares are not annual interest rates. The bank applies its contract, including day-count conventions and the withdrawal date. All three sampled products produce zero interest on day 90.
Compounding and deposit protection
Payment at maturity does not itself mean monthly capitalisation, so no compound interest is included. The Deposit Insurance Fund’s rules cap the protected manat interest rate at 12% and eligible individual compensation at AZN 100,000 per bank. The model balance is below that ceiling, subject to protection conditions. Multiple accounts at one bank do not create separate limits.
The practical choice
For money held until maturity, Yelo Sabit has the higher modelled net income in this sample. For money that may be required earlier, the relevant comparison is retained interest on the likely withdrawal date. Separating an accessible reserve from a term deposit avoids committing the entire cash buffer to one maturity.
