
As of 6 October 2026, the one-day interbank market rate AZIR was 5.7884%, while the yield on 28-day notes of the Central Bank of Azerbaijan at the auction on 7 October 2026 came in at 6.47%. Both values relate to the short segment of the money market, but they point to different levels of the cost of the manat for a term of up to one month: the interbank rate remains above the lower bound of the interest rate corridor of 5%, in effect since 24 September 2026, while the auction yield on the notes turned out to be below the policy rate of 6.5%, in effect since 5 February 2026. For a company planning short-term funding or placement of free manats, this means that there are two benchmarks, and they do not coincide.
What the rate levels show on specific dates
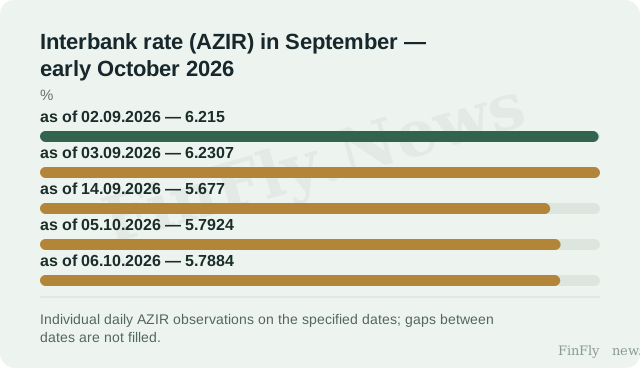
The comparison is based on individual observations, not on a continuous series. AZIR on 6 October 2026 — 5.7884%, the day before — 5.7924%; FinFly's calculation based on official observations gives a decline of 0.004 percentage points. Within September the spread is wider: 6.2307% on 3 September and 5.677% on 14 September. The lower bound of the corridor of 5% has been in effect since 24 September 2026; previously, from 5 February 2026, it was 5.5%, and the upper bound on the same date was 7.5%. The policy rate of 6.5% has been in effect since 5 February 2026.
The auction segment of the notes provides its own values: 6.47% at the auction on 7 October 2026 versus 6.5% at the auction on 30 September 2026; FinFly's calculation records a decline of 0.03 percentage points. An earlier observation — 5.63% at the auction on 29 July 2026. These are yield levels on the auction dates, not borrowing rates for business. The comparison is valid as a comparison of observations on dates, but not as a measurement of causes or a sustained trend.
Why these are different benchmarks for short-term funding
AZIR is the one-day interbank money market rate, that is, the price of money between banks for one day. The yield on 28-day CBA notes is the result of an auction for an instrument with a maturity of 28 days. These are different instruments with different terms and different price formation mechanics, so their levels do not have to coincide and do not confirm each other. If a company or bank chooses a benchmark for a transaction with a term of up to one month, it is logical to look at both values: the one-day rate describes the shortest end of the market, the auction yield — a slightly longer one.
The policy rate of 6.5% is the central bank's rate, not a loan or deposit rate for business. From the fact that the yield on the notes came in below it, it does not follow that lending conditions have changed: such a conclusion would require loan and deposit rates, transaction volumes and the reasons for the movements, which are not present in the provided observations. The practical conclusion is conditional: when planning short-term funding in manats, it makes sense to compare AZIR and the yield on the notes as two separate benchmarks, rather than substituting them with a single policy rate value.
The divergence between the one-day interbank rate and the auction yield on the notes is a difference in benchmarks, not proof of a change in the monetary policy course. AZIR on 6 October 2026 was 5.7884% and remains above the lower bound of the corridor of 5%, in effect since 24 September 2026; the yield on 28-day notes at the auction on 7 October 2026 — 6.47%, below the policy rate of 6.5%, in effect since 5 February 2026. For business, this means the need to work with two benchmarks for the short manat, not one.
