
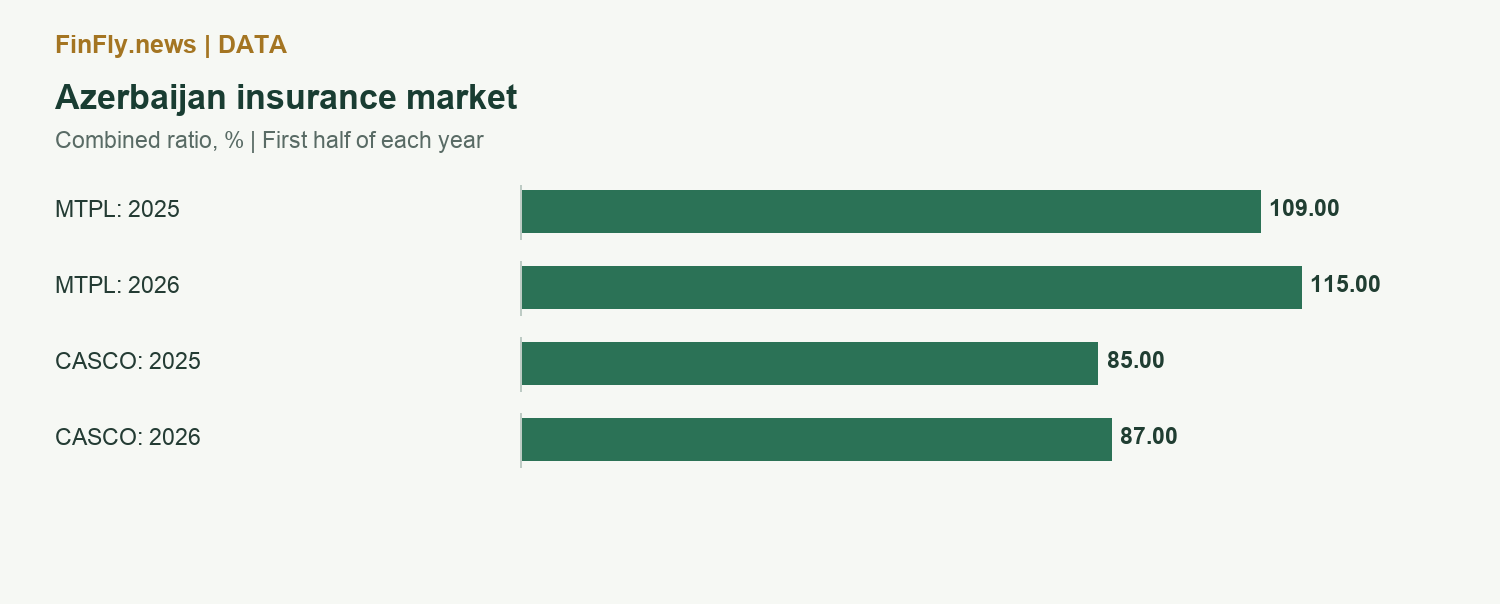
Compulsory motor third-party liability insurance has become one of the more pressured parts of Azerbaijan’s insurance market. Its combined ratio reached 115% in the first half of 2026, compared with 109% a year earlier, according to the Central Bank’s insurance-class calculations.
A combined ratio adds the loss and expense ratios. A reading above 100% means that the insurance losses and expenses captured by the measure exceed the corresponding premium base. It describes underwriting economics, not the final net profit of every insurer.
Lower expenses did not offset higher losses
The MTPL loss ratio increased from 80% to 87%. Its expense ratio declined from 29% to 28%, but that saving was insufficient. The combined measure consequently worsened by six percentage points.
Insurers can earn investment income and profits from other products. Neither changes the economics of MTPL itself: with this cost structure, selling more policies does not necessarily generate more underwriting profit.
| Segment | Loss ratio, % | Expense ratio, % | Combined, % |
|---|---|---|---|
| MTPL | 87 | 28 | 115 |
| CASCO | 55 | 32 | 87 |
Motor insurance is not a single market
CASCO’s combined ratio was 87%, against 85% a year earlier. Its loss ratio was 55% and its expense ratio 32%. The product covers different risks and has different terms and customers, so the gap with MTPL cannot be explained by price alone.
The Central Bank’s aggregate figures do not establish which factor increased loss costs: accident frequency, repair prices or reserve adjustments. A firm conclusion would require additional information on claim counts and average claim values.
What will determine the next result
Risk selection, claims handling and customer acquisition costs matter for insurers. A tariff change could also affect the outcome, but these statistics are not an announcement of such a decision.
For motorists, the financial figures provide context. Claims procedures and complaint indices need separate attention when comparing providers. An insurance class’s underwriting performance and the quality of customer service describe different aspects of the market.
