
Life insurers collected AZN 639.43 million in January–August 2026, approximately 57.3% of active insurers’ premiums. Yet this large segment is not uniform: savings-oriented products account for most of its business.
The Central Bank’s insurance-class breakdown records AZN 559.51 million in survival-policy premiums. Death protection generated AZN 28.47 million, critical illness AZN 7.21 million and disability AZN 2.09 million. Compulsory workplace-accident insurance contributed another AZN 42.15 million.
Much of the money is intended to return later
Survival policies pay customers when the contractual term or condition is reached. Their economics therefore involve long-term accumulation under insurance terms, rather than solely protection against a discrete event.
Payouts in this class reached AZN 561.65 million, compared with AZN 559.51 million in new premiums. That does not automatically establish a loss: some payments relate to older contracts and are funded from accumulated assets.
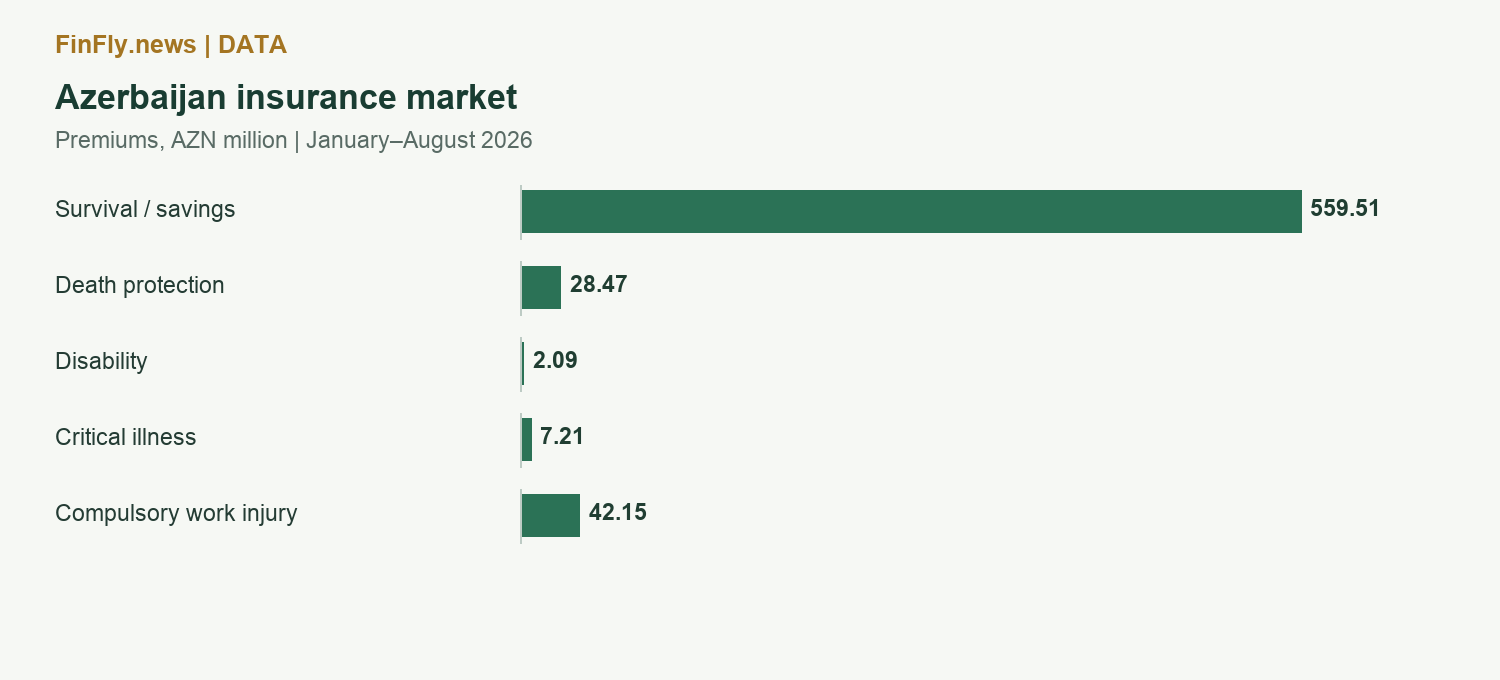
| Class | Premiums, AZN m | Payouts, AZN m |
|---|---|---|
| Survival / savings | 559.51 | 561.65 |
| Death protection | 28.47 | 2.58 |
| Disability | 2.09 | 0.08 |
| Critical illness | 7.21 | 1.27 |
| Compulsory work injury | 42.15 | 2.86 |
Today’s sales create obligations for future years
Strong savings-policy sales increase current cash inflows while creating future payment commitments. When a large cohort of contracts matures, payouts can accelerate without any deterioration in insured risks.
Portfolio age, maturity schedules and early-exit terms consequently matter. The public aggregate table does not disclose those details for each insurer, so it cannot establish a particular company’s funding gap.
Protection and savings need different comparisons
When assessing a savings product, contractual outcomes, duration and access to funds are important. For death or illness protection, covered events, exclusions and the insured amount deserve greater attention.
Combining both purposes under “life insurance” is convenient for statistics but insufficient for market analysis. Life insurance’s large share principally reveals the scale of savings business. It does not imply that a comparable share of the population has broad protection against every major life risk.
