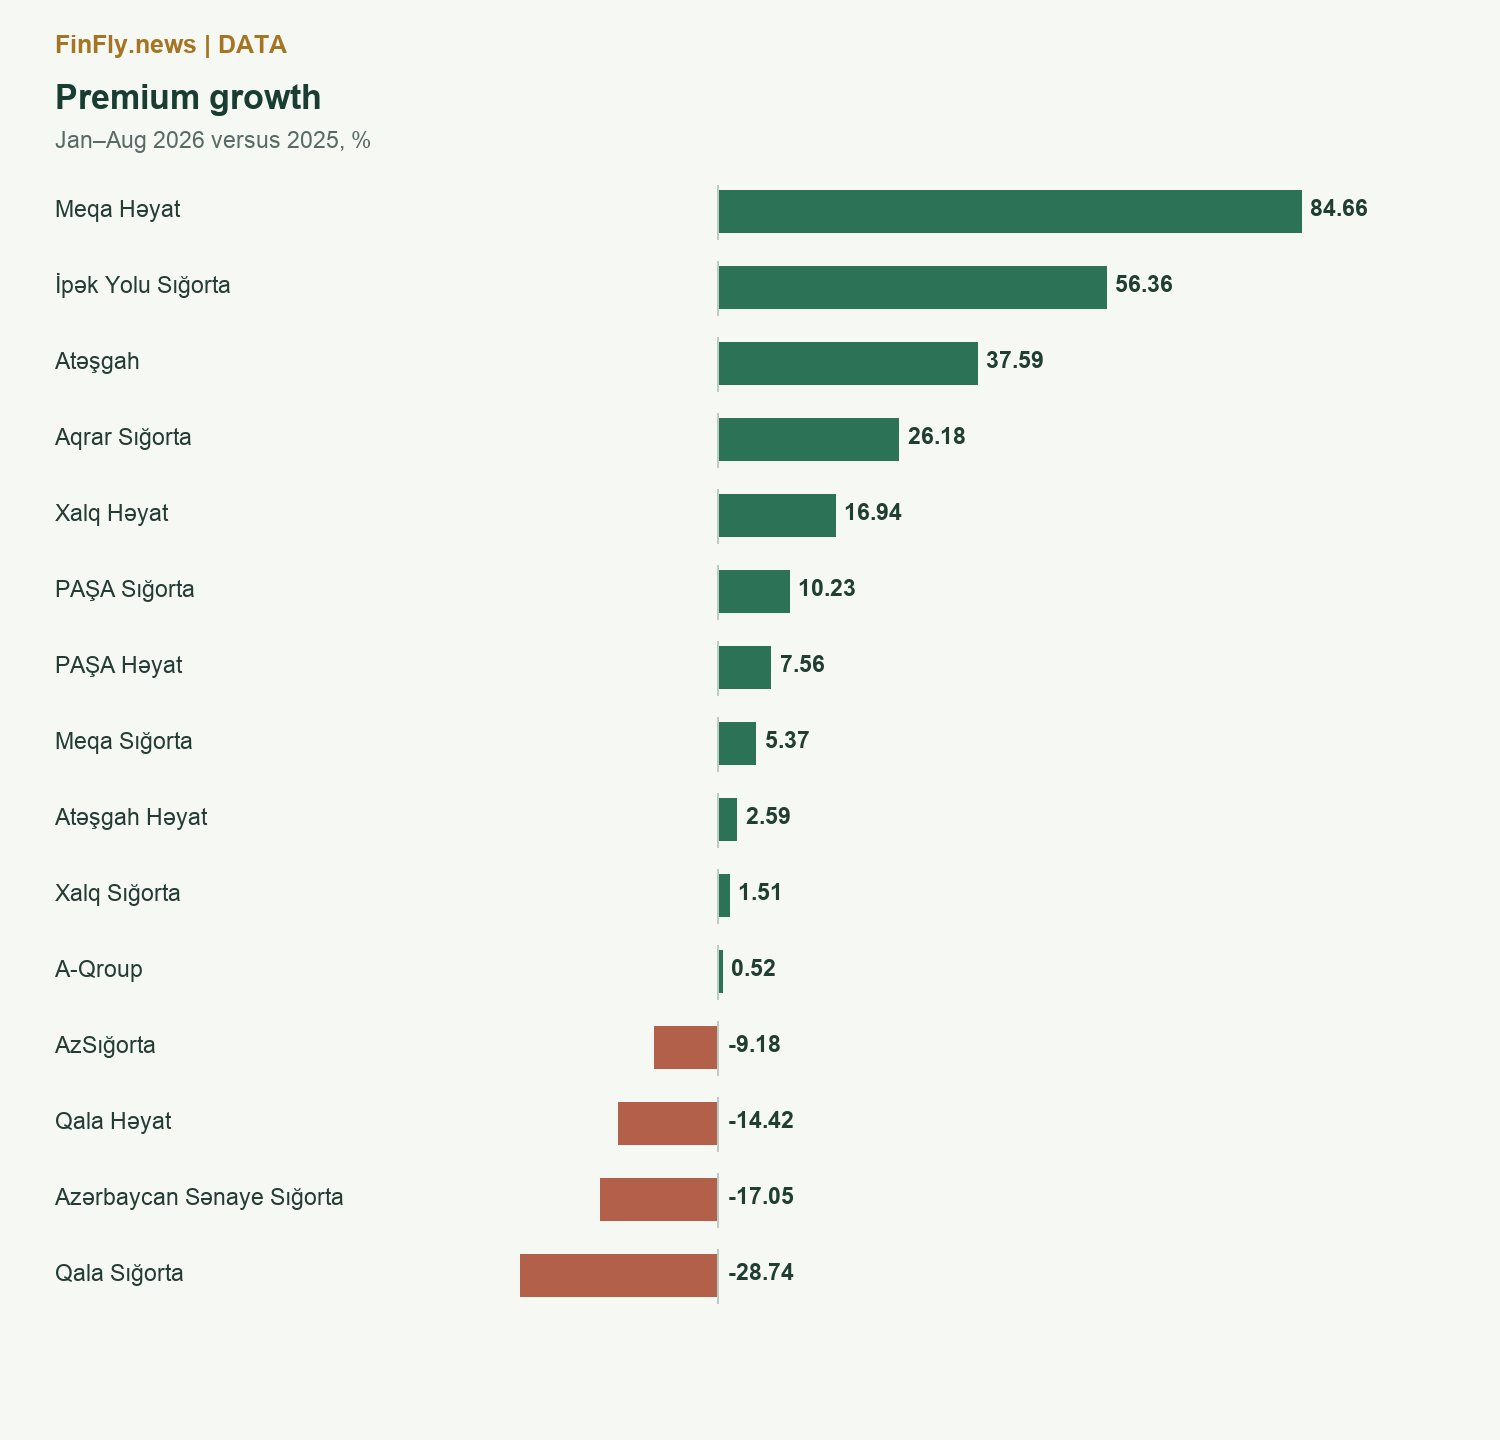
Meqa Həyat recorded the fastest premium growth among the 15 active insurers: its January–August 2026 premiums rose 84.7% to AZN 20.03 million. Qala Sığorta recorded the steepest decline, falling 28.7% to AZN 41.70 million. The calculations use the Central Bank’s comparable eight-month figures.
Percentages conceal differences in scale. Meqa Həyat added AZN 9.18 million, while PAŞA Həyat’s 7.6% growth generated an additional AZN 36.41 million. The fastest-growing insurer is therefore not the largest contributor to additional premiums.
A small base magnifies growth
İpək Yolu Sığorta increased premiums by 56.4% to AZN 6.52 million, an absolute increase of AZN 2.35 million. Atəşgah grew 37.6%, or AZN 16.06 million, reaching AZN 58.76 million.
Four participants recorded declines: Qala Sığorta, Azərbaycan Sənaye Sığorta, Qala Həyat and AzSığorta. Both the percentage movement and the absolute change are shown for each insurer below.
| Insurer | Growth, % | Change, AZN m |
|---|---|---|
| Meqa Həyat | 84.66 | 9.18 |
| İpək Yolu Sığorta | 56.36 | 2.35 |
| Atəşgah | 37.59 | 16.06 |
| Aqrar Sığorta | 26.18 | 4.03 |
| Xalq Həyat | 16.94 | 1.22 |
| PAŞA Sığorta | 10.23 | 25.36 |
| PAŞA Həyat | 7.56 | 36.41 |
| Meqa Sığorta | 5.37 | 1.23 |
| Atəşgah Həyat | 2.59 | 1.89 |
| Xalq Sığorta | 1.51 | 0.27 |
| A-Qroup | 0.52 | 0.06 |
| AzSığorta | -9.18 | -0.53 |
| Qala Həyat | -14.42 | -3.04 |
| Azərbaycan Sənaye Sığorta | -17.05 | -3.69 |
| Qala Sığorta | -28.74 | -16.82 |
Lower premiums do not always mean lost customers
The aggregate figure cannot identify whether contract numbers, prices, payment schedules or major corporate accounts changed. In savings-based life insurance, the cycle of existing and new contracts also matters.
Shrinking sales can accompany a decision to exit unprofitable business. Rapid growth can require additional reserves and spending. Neither movement should automatically be labelled a success or failure without examining the financial result.
What deserves closer examination
Companies combining strong percentage growth with a substantial increase in manats deserve particular attention. Their operating scale is changing, not merely their statistical base.
The next analytical step is to compare sales with payouts and capital over a matching period. That would help establish whether portfolio expansion is creating a sustainable business rather than simply increasing the volume of money passing through it.