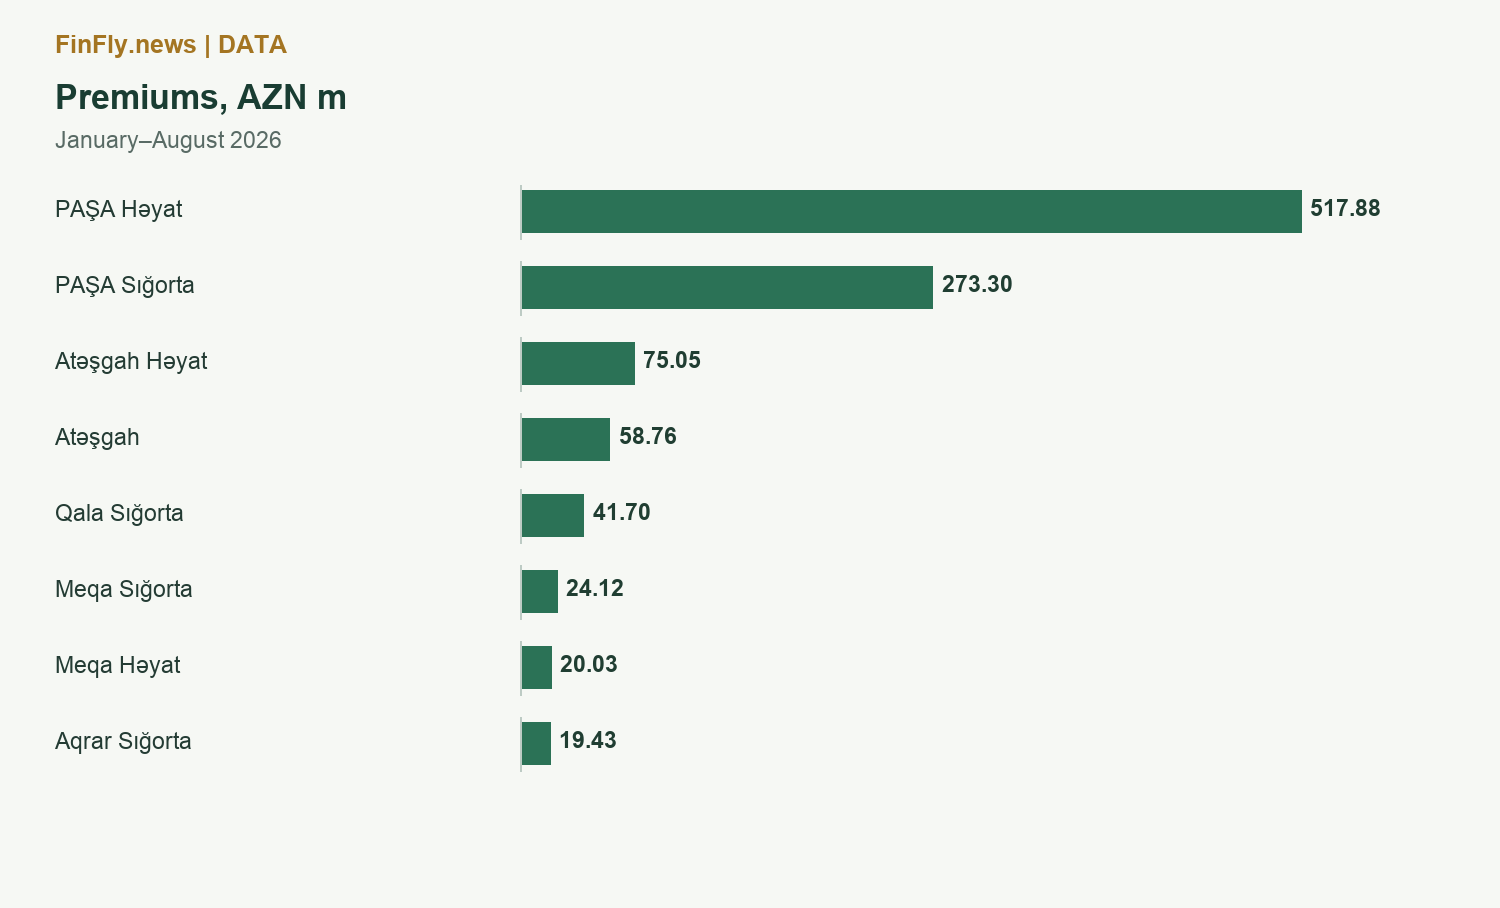
Two companies collect most of Azerbaijan’s insurance premiums. PAŞA Həyat recorded AZN 517.88 million in January–August and PAŞA Sığorta AZN 273.30 million. Together they represent about 70.9% of premiums collected by the 15 active insurers in the Central Bank’s company-level statistics.
Those insurers collected AZN 1.115 billion in total. The published market total also contains small receipts from companies with revoked licences. Market shares here use only the comparable group of active participants.
Compare leaders within their own segment
PAŞA Həyat accounts for approximately 81% of premiums among the five life insurers. Atəşgah Həyat follows with AZN 75.05 million. In non-life insurance, PAŞA Sığorta collects 57.4% of the ten companies’ premiums, followed by Atəşgah with AZN 58.76 million.
A combined list is useful for measuring scale, but not efficiency. A life savings contract and a property policy produce different cash flows. The full ranking below is consequently divided into two groups.
Life insurance
| Insurer | Premiums, AZN m |
|---|---|
| PAŞA Həyat | 517.88 |
| Atəşgah Həyat | 75.05 |
| Meqa Həyat | 20.03 |
| Qala Həyat | 18.03 |
| Xalq Həyat | 8.43 |
Non-life insurance
| Insurer | Premiums, AZN m |
|---|---|
| PAŞA Sığorta | 273.30 |
| Atəşgah | 58.76 |
| Qala Sığorta | 41.70 |
| Meqa Sığorta | 24.12 |
| Aqrar Sığorta | 19.43 |
| Xalq Sığorta | 18.32 |
| Azərbaycan Sənaye Sığorta | 17.97 |
| A-Qroup | 10.64 |
| İpək Yolu Sığorta | 6.52 |
| AzSığorta | 5.21 |
What scale can provide
A large portfolio can spread fixed costs across more contracts and support an extensive distribution network. Yet premium volume does not show how much remains after claims, reserves and expenses.
Customer concentration also matters. Winning a handful of large corporate contracts may deliver striking growth while increasing dependence on individual clients. Aggregate premium figures cannot establish how concentrated those relationships are.
Reading the ranking
Positions use the same eight-month period. Figures have been converted from thousands to millions of manats. This is a sales ranking, not a ranking of financial strength, profitability or claims speed.
A fuller comparison requires three further dimensions: premium growth, financial results and customer service. Size reveals where business is concentrated; it does not replace an examination of the insurance product being purchased.