
The monthly and year-to-date pictures diverge
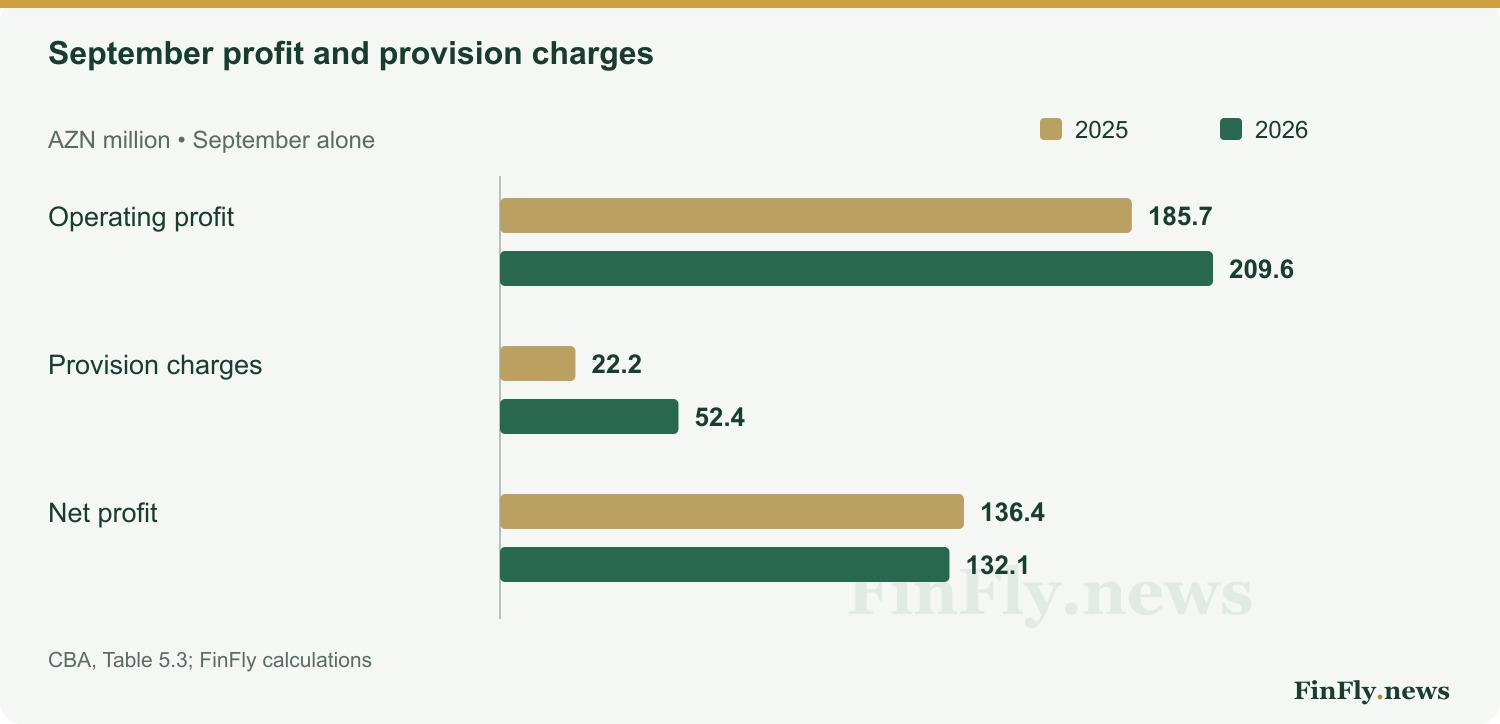
Azerbaijani banks earned AZN 132.1 million in September net profit, down from AZN 136.4 million a year earlier. FinFly calculated the 3.1% decline from the CBA’s banking-sector profit and loss statement by subtracting January-August totals from January-September totals in each year. This compares September with September, not with August.
Nine-month net profit nevertheless reached AZN 1.082 billion, against AZN 910.7 million a year earlier, an increase of 18.8%. One weaker month has therefore not reversed the year-to-date improvement. It does show why expanding income does not necessarily translate into higher bottom-line earnings.
Provisioning outweighed the operating improvement
September operating profit rose from AZN 185.7 million to AZN 209.6 million, or 12.8%. Charges for special provisions against possible asset losses, however, increased from AZN 22.2 million to AZN 52.4 million. The additional AZN 30.3 million charge exceeded the AZN 23.9 million operating-profit improvement.
Profit tax fell from AZN 26.7 million to AZN 24.9 million, cushioning part of the decline in net earnings. The sequence of reported line items points primarily to higher provisioning, rather than a contraction in operating income.
Deposit funding also cost more. September interest expense on deposits reached AZN 134.7 million, up 21.7% from AZN 110.7 million. Yet net interest income increased 14.3% to AZN 303.9 million. Higher interest expense alone does not establish that the net interest margin narrowed: that calculation also requires average interest-earning assets.
| Measure | 2025 | 2026 |
|---|---|---|
| Operating profit | 185.7 | 209.6 |
| Provision charges | 22.2 | 52.4 |
| Profit tax | 26.7 | 24.9 |
| Net profit | 136.4 | 132.1 |
What the figures can and cannot establish
Provision charges reduce current profit, but do not by themselves prove that loans have already become unrecoverable. They may reflect portfolio growth, credit quality or revised risk assessments. The aggregate table does not isolate those contributions or identify the banks responsible for the additional charges.
The next useful checks are subsequent monthly provisioning, impaired loans and capital. If operating earnings keep growing and provisioning stabilises, September may remain an isolated setback. If charges continue to outpace operating improvement, pressure on net profit will persist. These are analytical scenarios, not a CBA forecast.
Cover: an AI-generated editorial illustration by FinFly.news.
