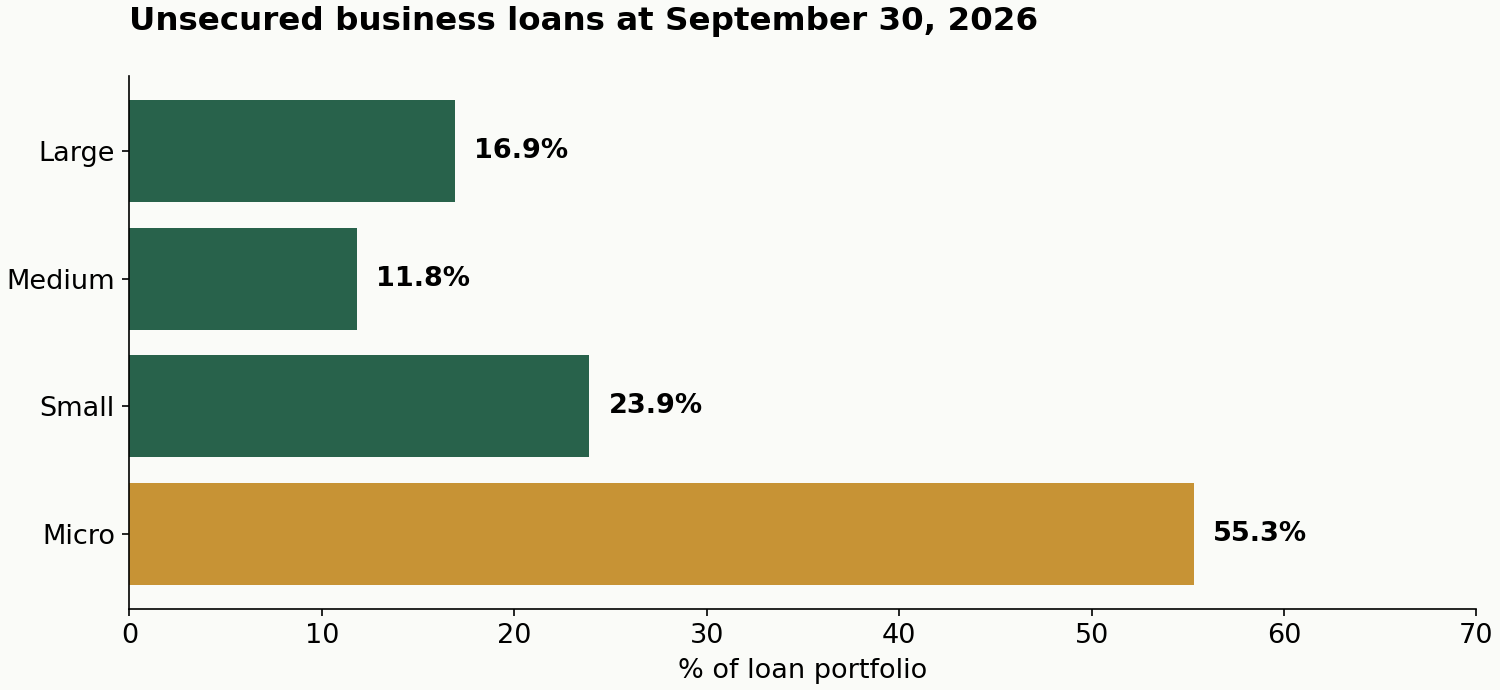
Unsecured loans account for 55.3% of Azerbaijan's bank lending portfolio to microbusinesses. This is the highest share among the four business-size groups in the CBA's September 30, 2026 breakdown. The equivalent share is 11.8% for medium-sized businesses and 16.9% for large companies.
The composition stands out: loans with some form of security make up a minority of the microbusiness portfolio. Across business lending as a whole, unsecured loans account for 27.3%.
Business size changes the portfolio mix
The CBA separates secured, partially secured and unsecured loans. For microbusinesses, the first two categories represent 25% and 19.7%, respectively. For medium-sized businesses, their combined share reaches 88.2%.
| Business size | Secured | Partially secured | Unsecured |
|---|---|---|---|
| Large | 58.0% | 25.1% | 16.9% |
| Medium | 52.0% | 36.2% | 11.8% |
| Small | 42.7% | 33.4% | 23.9% |
| Micro | 25.0% | 19.7% | 55.3% |
| All business loans | 45.3% | 27.4% | 27.3% |
A portfolio share is not an approval rate
The 55.3% figure describes the composition of outstanding lending. It does not mean that 55 out of every 100 entrepreneurs will obtain unsecured finance. The publication does not provide application or rejection counts, borrower numbers or the average loan size for each category.
Nor does the breakdown establish that microbusinesses receive better terms than medium-sized companies. That comparison requires rates, maturities, amounts and borrower characteristics. A high unsecured share could coexist with smaller limits or higher pricing, but this table cannot test that relationship.
What businesses can take from the figures
The data establish that bank financing without security is an existing part of microbusiness lending. They do not replace an assessment of an individual offer. A business needs to compare the available amount with its working-capital needs and check what monthly payment its revenue can support.
For lenders and support-program designers, the next substantive question is the amount and maturity available without security. Portfolio composition is a useful starting point. Application, approval and pricing data for the same business-size groups would provide a fuller assessment of access to finance.