
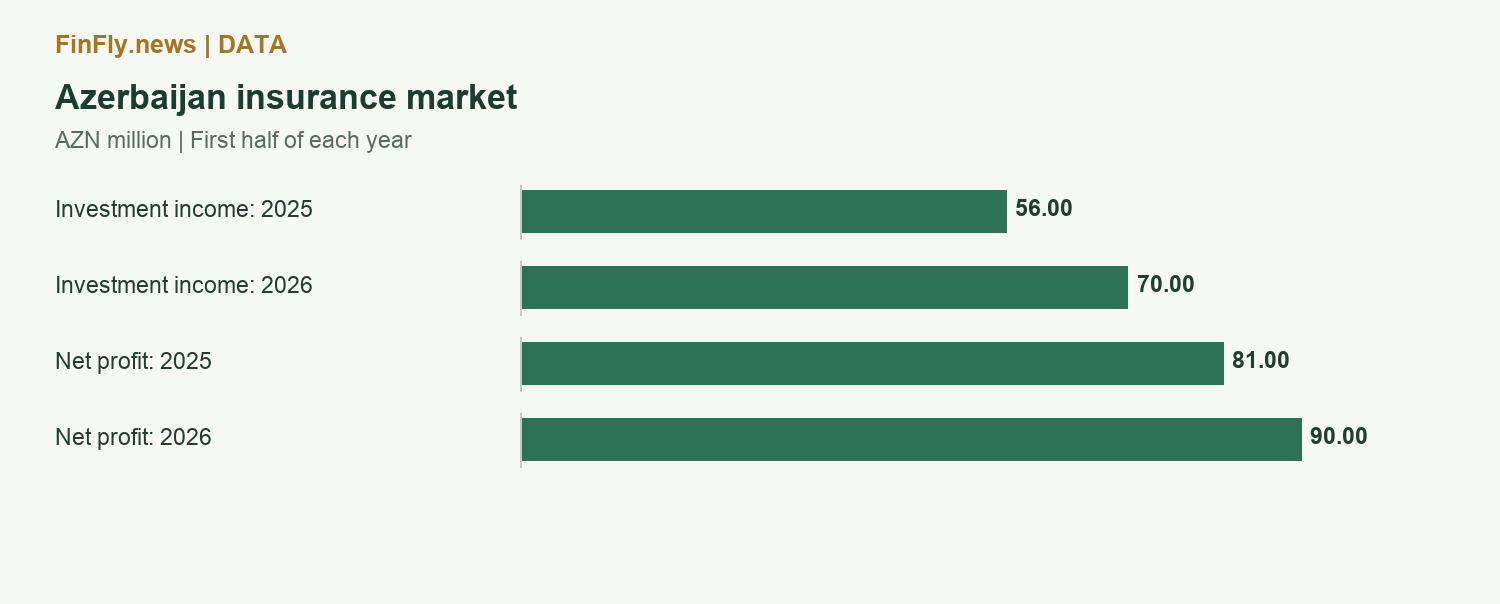
Azerbaijan’s insurance sector finished the first half of 2026 with net profit of AZN 90 million. The Central Bank reports an 11.9% year-on-year increase. Payouts nevertheless grew substantially faster than premiums, making the components of earnings important.
In the regulator’s first-half report, investment income rose from AZN 56 million to AZN 70 million. At the same time, the negative contribution from changes in net insurance reserves narrowed from AZN 173 million to AZN 86 million.
Revenue increased, but so did costs
Main operating income reached AZN 930 million, compared with AZN 809 million a year earlier. Main operating expenses rose from AZN 521 million to AZN 654 million. Business expenses increased more modestly, from AZN 146 million to AZN 151 million.
These items help explain the direction of change, but they are not a complete income statement. Adding rounded lines and calling the result net profit would be incorrect: the full accounts contain other adjustments and taxes.
| Measure, AZN m | H1 2025 | H1 2026 |
|---|---|---|
| Main operating income | 809 | 930 |
| Investment income | 56 | 70 |
| Change in net reserves | -173 | -86 |
| Main operating expenses | -521 | -654 |
| Business expenses | -146 | -151 |
| Net profit | 81 | 90 |
Investments matter more to earnings
The AZN 14 million increase in investment income is comparable in scale to the sector’s increase in net profit. That does not mean investments explain the entire improvement: reserves and insurance expenses changed simultaneously.
Investment earnings also expose insurers to interest rates and asset allocation. Returns available on new investments can differ from those earned by the existing portfolio. The current result therefore cannot simply be projected into the following year.
Life and non-life each earned AZN 45 million
The regulator reports AZN 45 million in profit for life insurers and the same amount for non-life insurers. Equal profit does not mean equal profitability: the groups have different asset, premium and capital bases.
Sustainability depends on repeatable earnings. Reserve effects and favourable investment conditions can support profit even when underwriting is under pressure. Net income should consequently be read alongside the combined ratio and changes in capital.
