
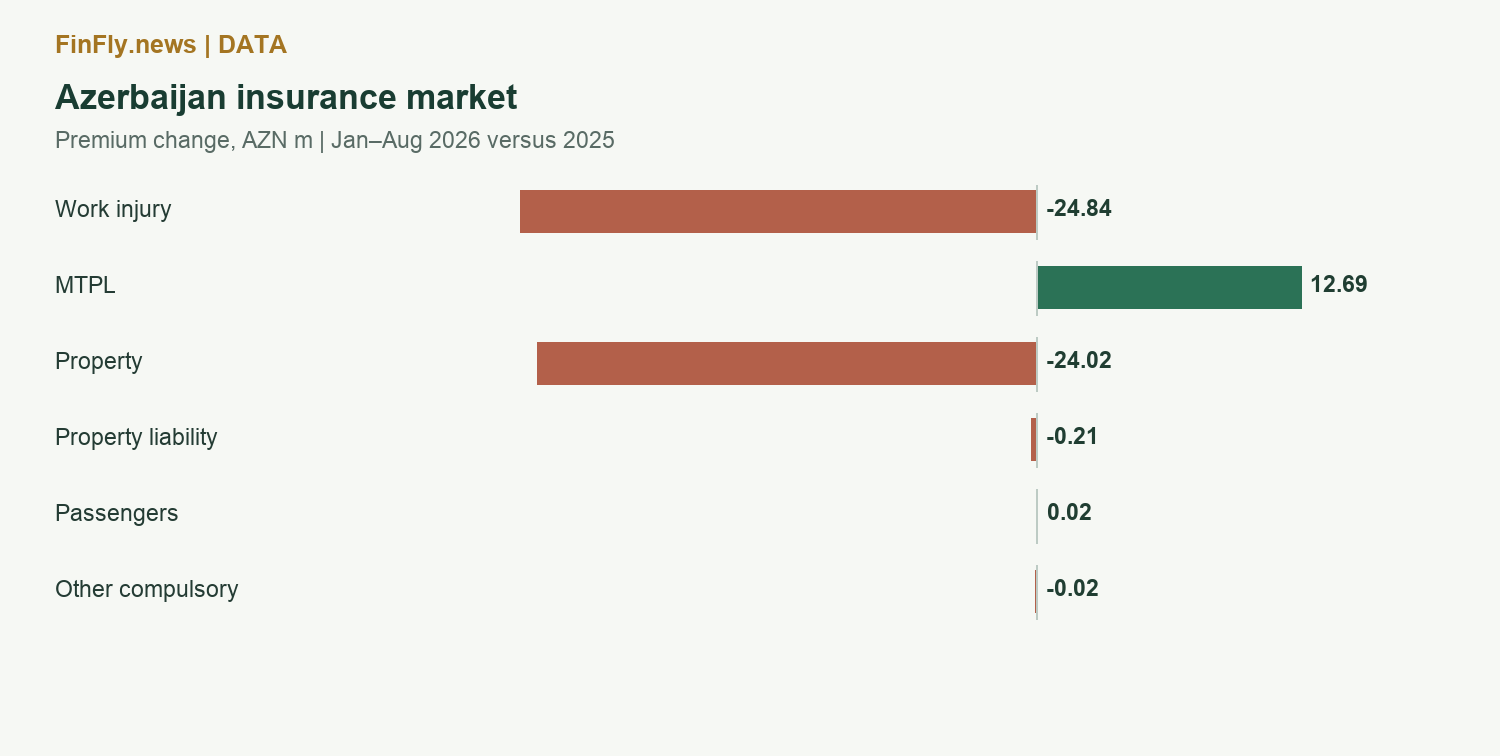
Compulsory insurance collected AZN 213.49 million in January–August 2026, down from AZN 249.86 million a year earlier. That is a decline of AZN 36.37 million, or 14.6%. Individual classes moved in different directions, however, as shown in the Central Bank’s insurance-class statistics.
MTPL, the largest compulsory class by current premiums, grew by AZN 12.69 million to AZN 131.23 million. Attributing the overall compulsory-market decline to falling motor premiums would therefore be incorrect.
Two classes explain the contraction
Compulsory property premiums fell from AZN 63.32 million to AZN 39.30 million, a decline of 37.9%. Insurance against workplace accidents and occupational diseases lost AZN 24.84 million, falling to AZN 42.15 million.
Together, these classes contracted by almost AZN 48.85 million. MTPL growth partially offset the decrease. The other compulsory categories account for much smaller amounts.
| Class | 2025, AZN m | 2026, AZN m | Change |
|---|---|---|---|
| Work injury | 66.99 | 42.15 | -37.08% |
| MTPL | 118.53 | 131.23 | 10.71% |
| Property | 63.32 | 39.30 | -37.93% |
| Property liability | 0.88 | 0.66 | -24.29% |
| Passengers | 0.11 | 0.13 | 16.40% |
| Other compulsory | 0.04 | 0.02 | -45.02% |
What the table cannot establish
Premium figures do not reveal whether the decline reflects fewer insured properties or employees, pricing, payment schedules or large contracts in the previous year. Nor can they directly establish a reduction in actual insurance protection.
The distinction matters for businesses. A payment-date shift changes the reported flow without necessarily changing coverage. Properties leaving insurance altogether would change the underlying market. Those explanations call for different responses.
Greater dependence on motor liability
MTPL now represents approximately 61.5% of compulsory premiums, compared with 47.4% a year earlier. The market is therefore changing composition as well as shrinking. Its aggregate performance depends more heavily on a single product.
Higher MTPL sales are not the same as higher profit: the Central Bank’s first-half report placed its combined ratio above 100%. Product volume and underwriting economics need to be assessed separately.
