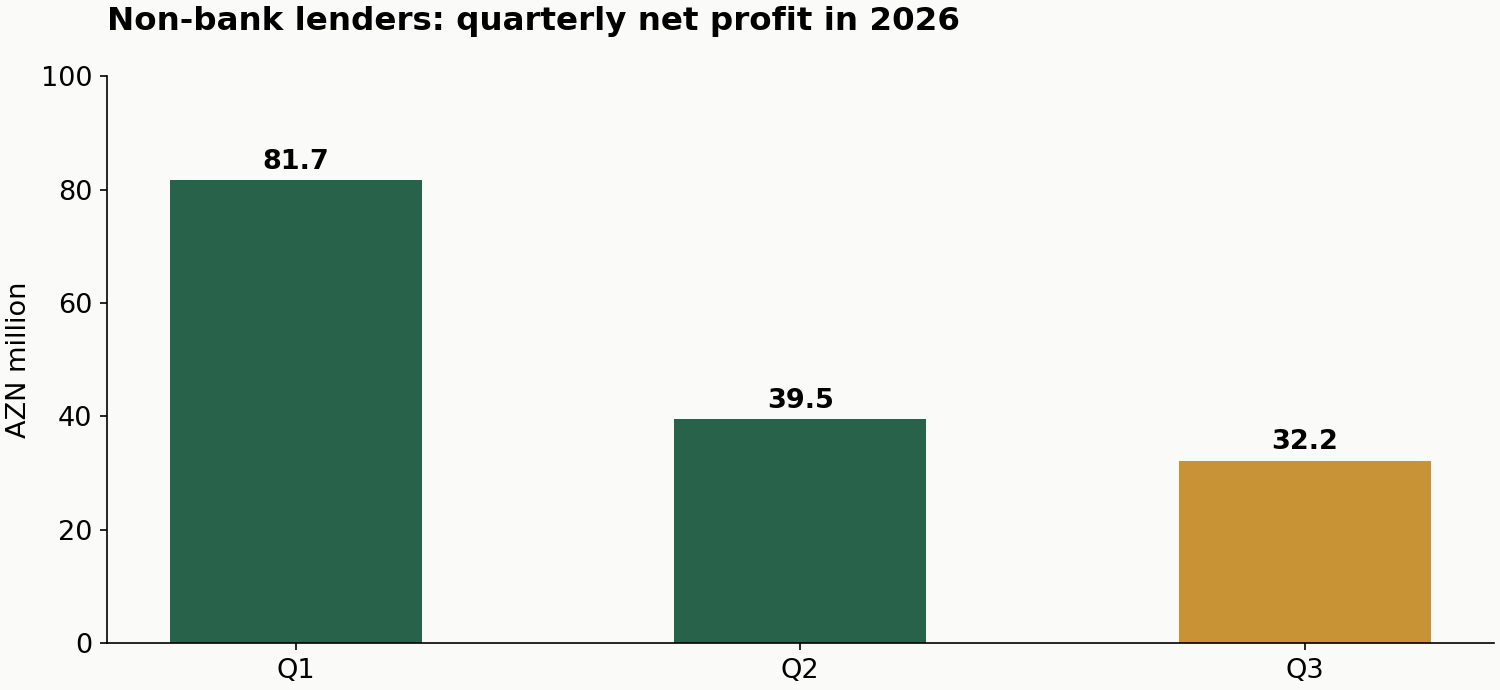
Azerbaijan's non-bank credit institutions earned AZN 153.4 million in the first nine months of 2026. More than half of that result came in the first quarter. Profit in July-September was AZN 32.2 million, down 18.5% from April-June.
FinFly calculated the quarterly figures from the CBA's cumulative income statement, subtracting first-half results from the nine-month total and first-quarter results from the first-half total. The series excludes Aqrarkredit.
Annual growth masks a weaker quarterly result
Nine-month profit was 2.54 times the result for the same period of 2025. Within 2026, however, the sequence was AZN 81.7 million in the first quarter, AZN 39.5 million in the second and AZN 32.2 million in the third. The opening quarter accounted for 53.3% of nine-month profit.
The annual comparison therefore gives an incomplete picture of the sector's current earnings pace. The sequential comparison shows that lenders ended September with a lower quarterly net result than in spring.
| AZN million | Q2 2026 | Q3 2026 |
|---|---|---|
| Operating profit | 97.1 | 98.2 |
| Asset loss provisioning charges | 52.8 | 57.2 |
| Income tax | 5.0 | 8.7 |
| Net profit | 39.5 | 32.2 |
Operating profit held up
Quarterly operating profit increased by AZN 1.1 million. The decline emerged further down the income statement: provisioning charges rose by AZN 4.4 million and income tax by AZN 3.7 million. A separate line for other adjustments and prior-period results contributed a further AZN 0.3 million deterioration.
Together, these movements reconcile the AZN 7.3 million fall in net profit. Provisioning is an expense for potential asset losses during the reporting period. It is not a measure of overdue loans.
The earnings pace matters for further growth
Repeatable earnings matter when assessing how much expansion a lender can finance internally. Nine-month profit remains substantial, but its quarterly average would be a premature forecast for the final quarter: actual third-quarter earnings were about 37% below that average.
The next statement will show whether provisioning costs stabilize and how much operating profit remains after provisions and tax. The available figures describe a profitable sector with weaker quarterly earnings. As a sector aggregate, the report does not establish the performance of each individual lender.