
Domestic cashless card transactions reached about AZN 8.98 billion in September, against AZN 3.94 billion in cash withdrawals. Cashless value was more than twice as large.
Cashless value leads within the card system
A calculation from CBA Table 4.5 gives AZN 12.92 billion in domestic card turnover. Cashless transactions account for AZN 8.98 billion, approximately 69.5%. ATM and POS cash withdrawals make up the remaining 30.5%.
The cashless total includes e-commerce, POS payments, ATM payments and self-service terminals. Foreign transactions are excluded, allowing the two uses of cards to be compared within the same geography.
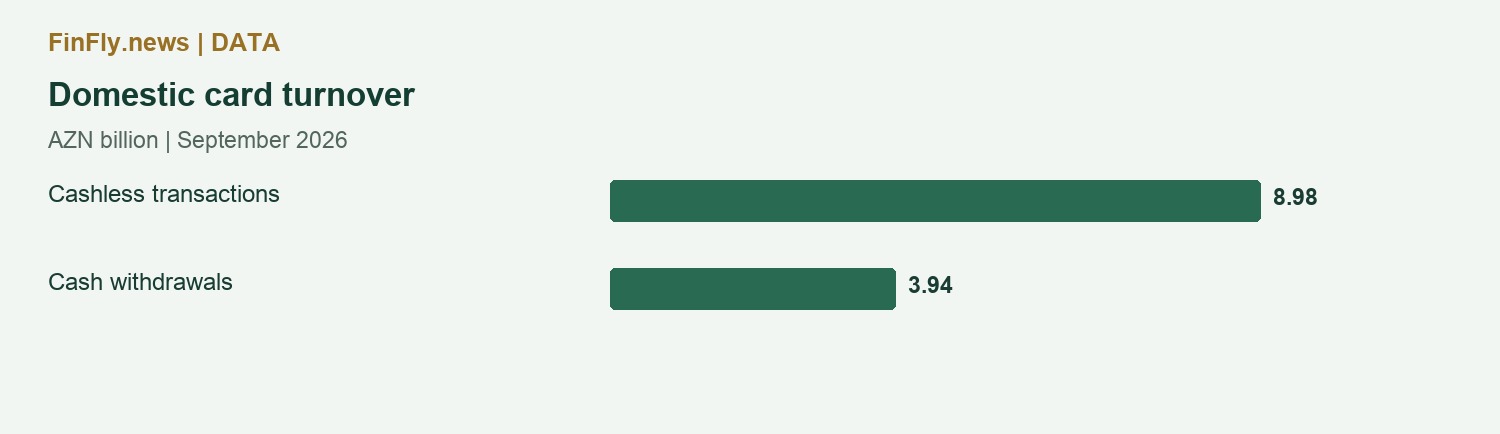
Cash still has a substantial role
September ATM withdrawals were AZN 3.79 billion, with another AZN 148.3 million withdrawn through POS terminals. Together they totalled nearly AZN 3.94 billion, against AZN 3.93 billion in August. Cashless growth does not mean cash demand has disappeared.
POS payments reached AZN 1.22 billion and e-commerce AZN 7.76 billion. Contactless payments are a subset of POS turnover; adding them separately would overstate the total.
| Component | September, AZN million |
|---|---|
| ATM withdrawals | 3,792.30 |
| POS withdrawals | 148.33 |
| POS payments | 1,219.71 |
| E-commerce | 7,755.42 |
| Other cashless channels | 1.88 |
What the 69.5% share does not mean
The measure covers card transactions, not the whole economy. It excludes purchases using cash obtained outside the card system and separate types of bank transfer.
Merchants also care about acceptance costs and settlement speed. The cashless share demonstrates the scale of card infrastructure, but is not the cashless share of all sales or a measure of retail revenue.
